Auction Price vs Retail Sticker

What the Used-Car Price Gap Actually Pays For

SEPTEMBER 2026 EDITION

A used SUV rolls through a dealer-only auction lane on a Wednesday morning in Pennsylvania. The tires are decent. The Carfax looks clean enough. The condition report says "minor prior paintwork," and the hammer falls at $18,400. Three weeks later, a similar SUV shows up online for $24,995, and that's before taxes, title, doc fee, registration, and whatever else gets folded into the out-the-door number.

That gap makes buyers suspicious. Fair enough. For years, people have been told dealers "buy cheap and sell high," as if the distance between wholesale and retail were a magician's pocket. Sometimes it's too fat. Sometimes it's justified. Often, it's a messy ledger of transport, auction fees, recon, financing risk, title work, advertising, payroll, warranty exposure, and plain old profit.

The post-pandemic market sharpened the question. Wholesale values in the USA spiked violently during the inventory crunch, then cooled as new-car supply recovered. Retail prices didn't always fall as fast. Buyers noticed. They had spreadsheets, browser tabs, payment calculators, Reddit threads, and a growing impatience with pricing they couldn't see through.

Here's the thing, though. The auction-to-retail spread isn't automatically a rip-off. A dealer isn't merely reselling a car. The dealer is converting an uncertain wholesale asset into something you can inspect, finance, register, sometimes return, and drive home without becoming a part-time title clerk. That conversion costs money.

"The real question is narrower: what does the spread pay for, and when does it stop being value and start becoming padding?"

The useful version of the question is tighter than most shoppers frame it. What exactly does the spread pay for, and where does the line sit between value and padding?

Why Stickers Sit Above Auction

Dealer-only auctions aren't consumer showrooms. They're wholesale marketplaces built around speed, risk tolerance, and imperfect information. A lane may move dozens of vehicles in an hour. Digital auctions move faster still. Buyers lean on condition reports, paint meter readings when they exist, seller announcements, arbitration rules, and their own scars from previous bad buys. Nobody is taking a leisurely Saturday test drive with a latte in the cupholder.

When a vehicle leaves auction, the purchase price is only the first line item. The buyer usually pays auction fees, transport, possible storage, title handling, and floorplan interest if the inventory is financed. Then comes reconditioning. People toss that word around casually, but it can mean anything from an oil change and windshield repair to brakes, tires, suspension work, emission-system repairs, dent removal, key replacement, software updates, and a hybrid battery that throws a warning light the day after arrival.

Operators talk about recon in a broad range, often a few hundred dollars for a clean late-model trade, sometimes $2,000 or more on an older unit that needs rubber, brakes, cosmetics, and diagnostic labor. Trucks can be worse. Luxury German cars can be much worse. A $1,100 set of tires doesn't care what the auction estimate said. Truck reconditioning can be especially costly, making Used Trucks a useful comparison for shoppers evaluating wholesale-to-retail spreads.

Then there's merchandising. Photos, descriptions, history reports, listing feeds, pricing software, phone staff, lead management, lot insurance, compliance paperwork, and the person who deals with you after the sale when the infotainment screen freezes. Retailing is expensive. Annoyingly expensive.

The sticker also embeds risk. A dealer may sell "as-is" where allowed, but that doesn't erase reputational risk, chargebacks, state disclosure obligations, warranty claims, or the practical cost of making an angry buyer whole. FTC Used Car Rule requirements, Buyers Guide disclosures, odometer statements, title branding rules, and state-specific dealer regulations all shape the price. In California, emissions and compliance concerns change what a dealer will buy and how much must be spent before sale. In states with annual safety inspections, marginal brakes or tires aren't a suggestion. They're a bottleneck.

The spread is a bundle, not a single fee

Break the gap apart and it looks less mysterious. Auction acquisition cost sits at the center. Around it orbit transport, auction fees, recon, title and registration workflow, flooring interest, advertising, sales pay, warranty reserves, overhead, taxes collected for the state, and margin. Some of those charges create direct buyer value. Some just keep the machine running.

  • Mechanical inspection and reconditioning, especially brakes, tires, fluids, warning lights, recalls, and drivability issues.
  • Cosmetic prep, though you should be wary of cars polished into artificial perfection. A market for no paint correction used cars exists because original surfaces often tell a more honest story.
  • Transport and logistics from auction lane to recon facility, then to store or buyer.
  • Title, lien, odometer, and state registration processing.
  • Financing administration, lender stipulations, funding delays, and the risk of unwinds.
  • Dealer overhead, advertising, compliance, and profit. Yes, profit belongs on the list. Businesses aren't charities.

The trouble starts when you can't see which bucket your money is filling. A $4,500 spread may be perfectly reasonable on a hard-to-find one-owner Tacoma that needed tires, brakes, and a clean title transfer from another state. The same $4,500 on a high-mileage sedan bought clean, barely serviced, and shot under flattering lights? That's a different story.

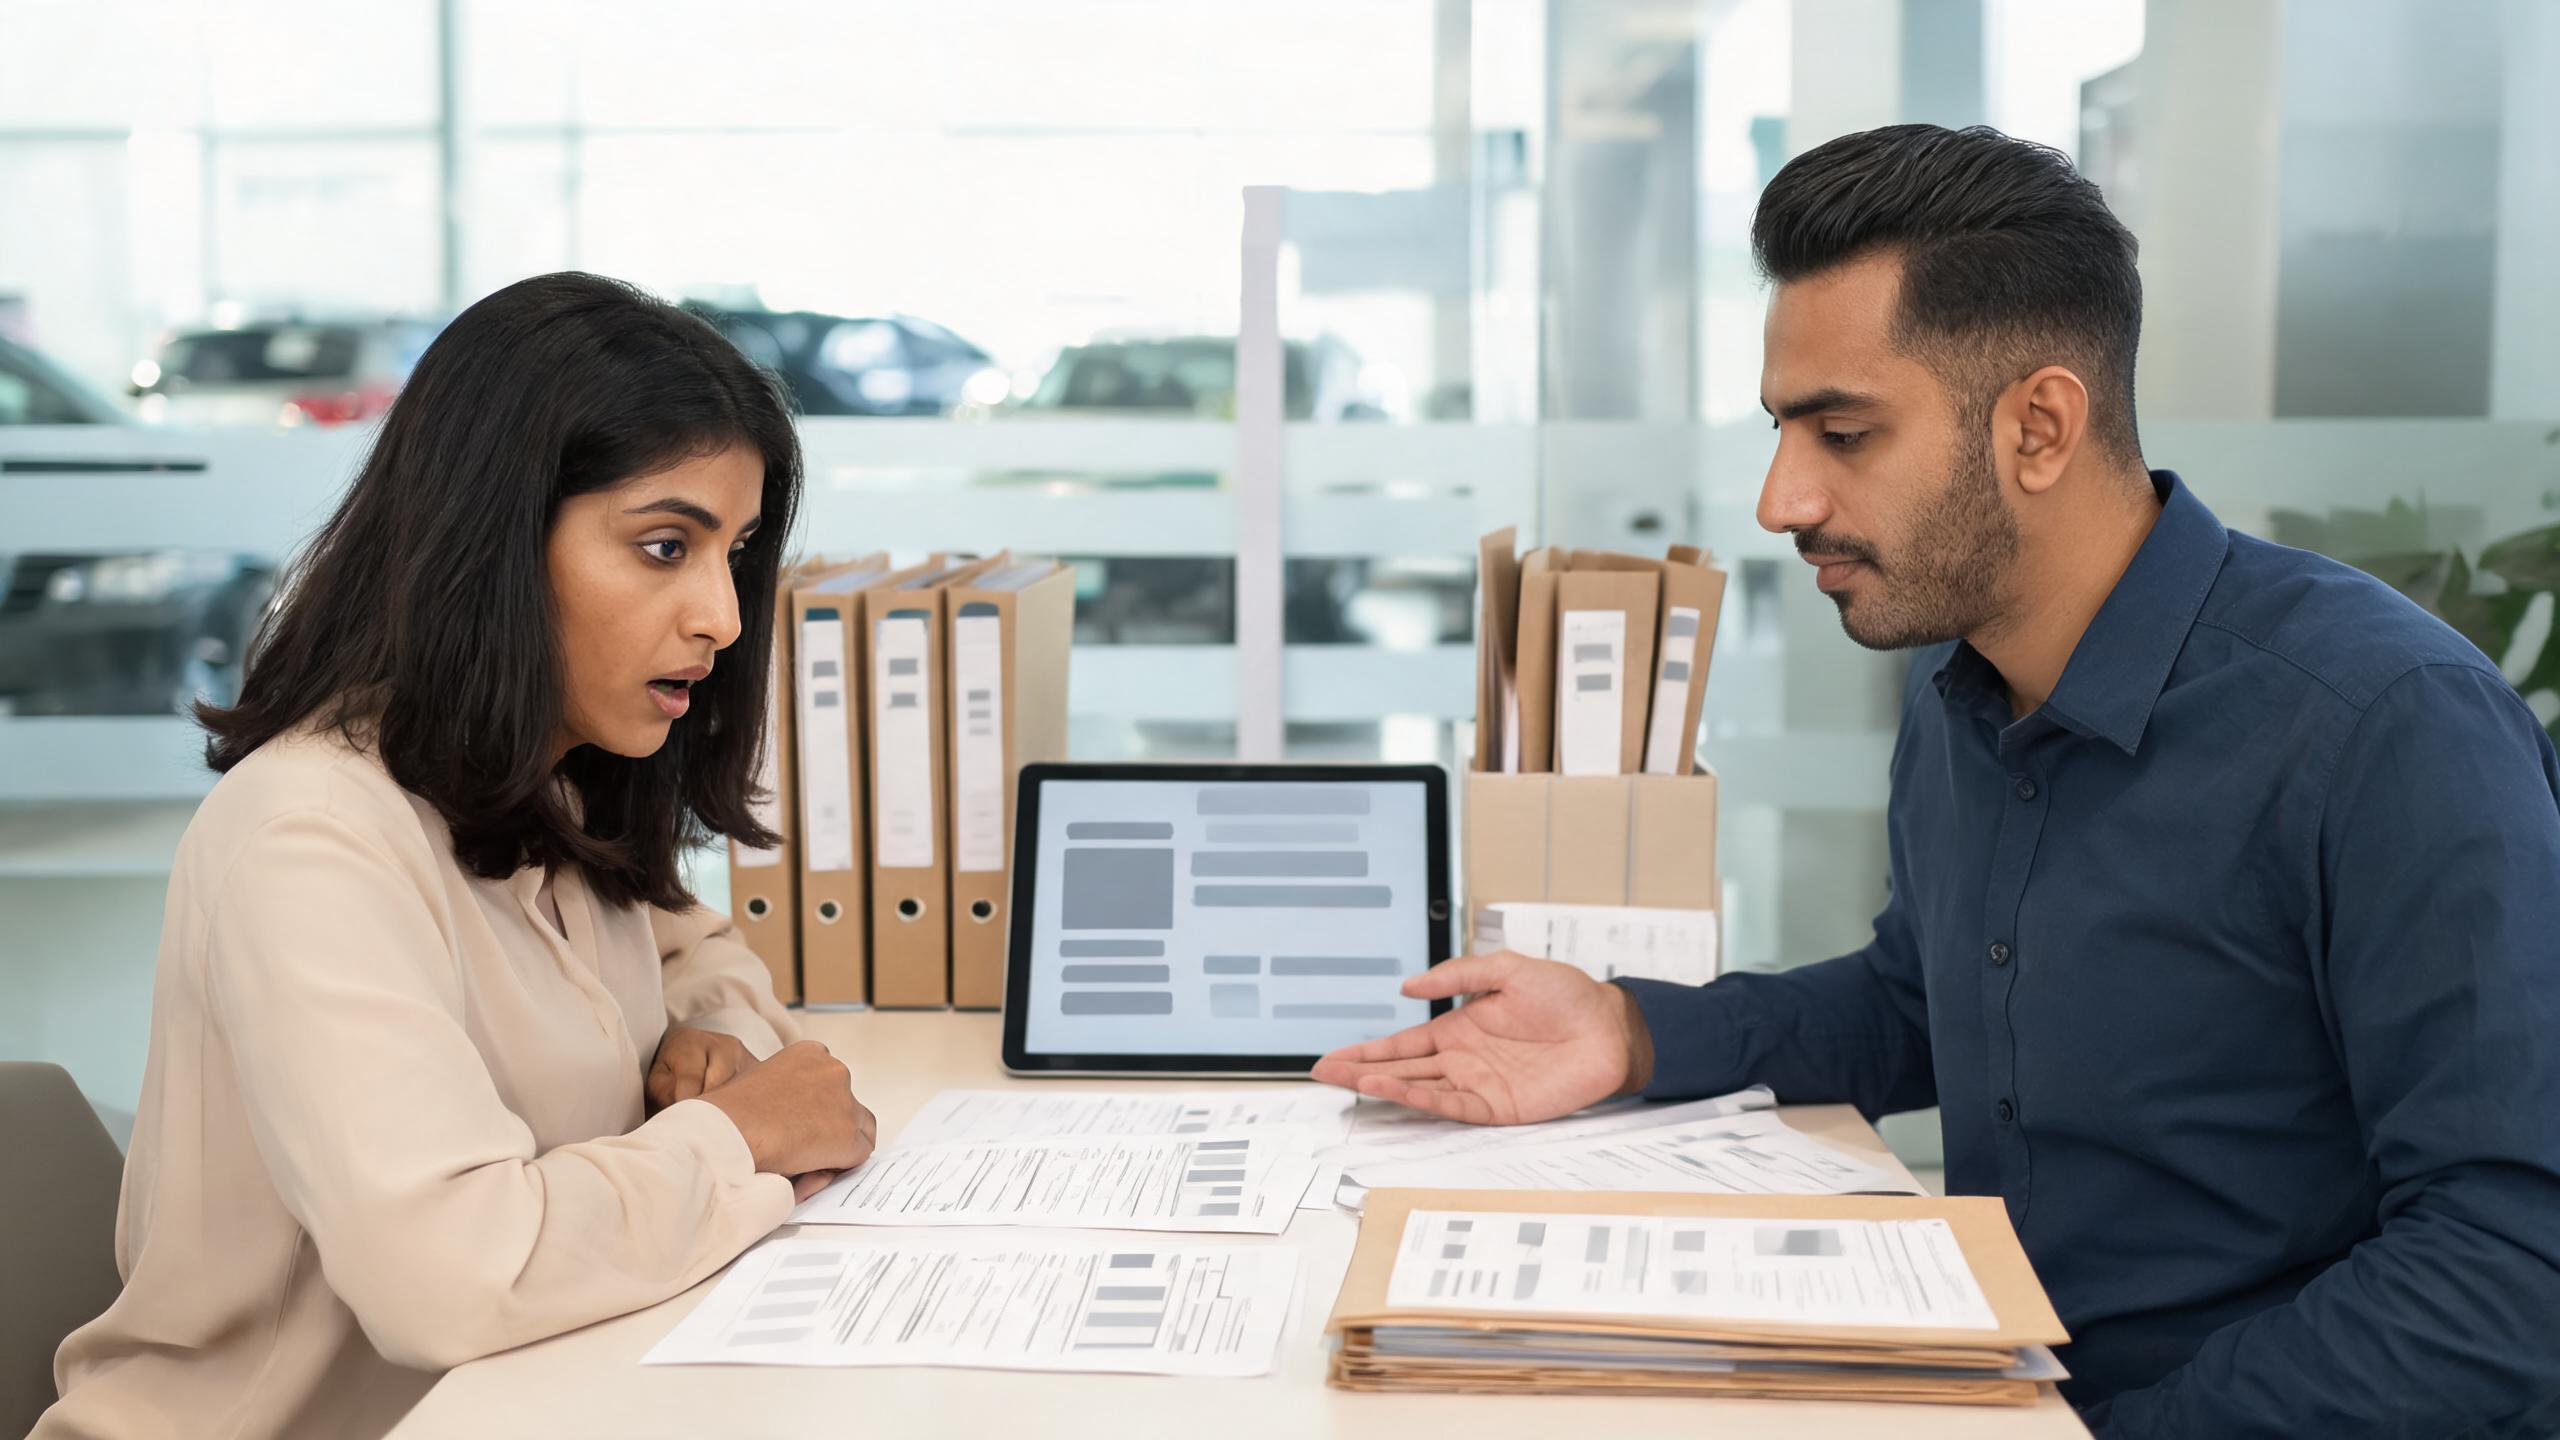
Buyer and finance manager reviewing fees beyond the sticker price, explaining how the out the door price car total includes taxes, title, registration, and optional products.

Out-the-Door Math

Where Buyers Get Misled

The sticker isn't the deal. The out the door price car buyers actually pay includes the vehicle price plus sales tax, title, registration, state fees, doc fees, and any optional products the buyer accepts. In the USA, that final number swings hard by state and even municipality. A buyer in Oregon faces a different tax picture than someone in Illinois, Texas, or Florida. Registration charges, electronic filing fees, tire fees, and doc fee caps can turn a simple comparison into a small accounting project.

Dealers know most shoppers anchor on the monthly payment. That's dangerous when rates are high. Experian's auto finance reporting in recent years has shown average used-car loan rates sitting in the low double digits, with subprime borrowers often paying far more. A $2,000 difference in selling price hurts. A high APR stretches that pain across five or six years and disguises it as "only" another $40 or $50 a month.

"Add a service contract, GAP, and a doc fee, and a $22,000 car quietly becomes a financed balance closer to $27,000 before interest."

Payment shopping also blurs the auction-retail gap. Mark a vehicle up $3,000 but stretch the term from 60 to 72 months, and the monthly quote looks tolerable while the total cost turns ugly. That's before the money you'll spend after you drive off; the true cost of car ownership keeps climbing long after the ink dries.

This is one reason buyers keep asking why Carvana is expensive. The answer isn't one thing. Large online retailers carry national logistics, inspection centers, return policies, digital advertising, customer acquisition costs, inventory financing, and public-market pressure to generate gross profit. Convenience has a price. So does a seven-day return window. The catch is that people compare a glossy online number to an auction benchmark and forget the online model has its own expensive plumbing behind the screen.

Comparison shopping has shifted the balance, though. Ten years ago you might visit three lots and trust your gut. Now retail listings, auction anecdotes, valuation tools, lender preapprovals, and insurance quotes sit side by side in a browser. The fog is thinning. Slowly. But it's thinning.

Fees deserve daylight

Some fees are legitimate. Some are theatrical. State registration costs are real. Sales tax isn't a dealer windfall. Title processing takes labor. But vague "protection packages," pre-installed accessories, nitrogen, VIN etching, mandatory ceramic coatings, and inflated recon fees deserve scrutiny, especially when they surface late in the deal. If you want a map of what you can push back on, read up on which doc fees, prep fees, and dealer add-ons you can refuse.

A serious buyer asks for the full out-the-door price in writing before visiting or leaving a deposit. Not an estimate. Not "plus TTL." The full number. If the dealer refuses, that tells you something. Maybe everything.

  1. Request the selling price, doc fee, taxable add-ons, taxes, title, registration, and lender fees separately.
  2. Ask whether any accessories or protection products are mandatory.
  3. Compare insurance quotes before committing; premiums have climbed sharply in many markets and can wreck affordability.
  4. Get a preapproval from a bank or credit union, then let the dealer try to beat it.
  5. Review the Buyers Guide, title status, odometer disclosure, and any warranty terms before signing.

The Wholesale Alternative

Car Auction Access for Buyers in the USA

Most consumers can't stroll into Manheim, ADESA, or a closed dealer auction and bid like a licensed pro. The system was designed for wholesale operators, not retail shoppers. Dealer licensing, bond requirements, state regulations, tax rules, arbitration procedures, and payment timelines all form a wall. That wall protects the auction ecosystem, but it also leaves ordinary buyers watching from outside while wholesale prices set the market.

Buyer-side wholesale acquisition is one answer. Instead of browsing a retail lot, you work with a specialist that sources vehicles through dealer-only channels, inspects candidates, estimates recon honestly, handles financing and paperwork, and arranges delivery. VirtualCarHub.com is an example of that model: no retail lot, no commissioned salesperson pushing aged inventory, no traditional markup layered onto a storefront.

The appeal is obvious. If you can reach wholesale supply and pay transparently for acquisition, inspection, logistics, and administration, the math shifts. You won't capture every dollar between auction and retail; nobody should pretend auctions are risk-free treasure chests. But you can skip some retail overhead you don't need. Prime-location lot rent. Sales commissions. Bloated advertising. The cost of inventory sitting under lights for 47 days.

There's a catch. Wholesale access only works when the process stays disciplined. Bidding emotionally at auction is how professionals lose money too. A clean photo set can hide prior paintwork. A "green light" sale can still need recon. A southern truck may have sun-baked trim, a northern SUV may carry corrosion underneath, a coastal vehicle may show salt-air wear in places you rarely check. If you're bidding sight-unseen, learn to spot flood or salvage damage before you buy at auction. Regional differences matter here because climate, road salt, emissions rules, and local demand all shape value.

Original-owner inventory and honest condition

Buyers often ask for original owner used cars wholesale because single-owner history suggests better continuity of care. It's not a guarantee. A one-owner car can be neglected, smoked in, or serviced only when something screamed. Still, an original-owner vehicle with documented maintenance, clean title history, consistent mileage, and no suspicious auction announcements tends to deserve a stronger bid. Shoppers prioritizing documented ownership history can compare available Used Sedans while assessing maintenance continuity.

Paint works the same way. Retail lots make cars look almost too good: heavy correction, gloss enhancers, wheel refinishing, engine-bay dressing, photography that flatters every curve. Nothing wrong with cosmetic prep, but aggressive polishing erases clues. Serious buyers sometimes prefer no paint correction used cars during inspection, because original clear coat, scratches, chips, and panel texture reveal how the car actually lived.

"For buyer-side acquisition, best practice looks less like bargain hunting and more like underwriting."

Set a ceiling bid based on expected retail value minus recon, fees, logistics, and a risk reserve. Pull vehicle history before bidding. Read seller announcements like a lawyer. Reject units with title ambiguity, structural damage, odometer inconsistency, unresolved safety issues, or unexplained electronic faults. And never fall in love with a VIN.

VirtualCarHub.com's angle is useful because the buyer-side model forces a different conversation. The question isn't "How much gross can this unit hold?" It's "Can this specific vehicle be acquired, verified, financed, documented, and delivered at a total cost that beats retail while keeping the buyer protected?" That's a tighter standard than most shoppers expect.

What the Gap Looks Like by Segment and Region

The auction-retail spread isn't uniform. Late-model pickups in Texas, Oklahoma, and the Mountain West often command stubborn retail prices because utility demand is real. Contractors, ranch owners, boaters, and suburban families all compete for the same half-tons and body-on-frame SUVs. A clean F-150, Silverado, Tundra, or 4Runner can bring aggressive wholesale money and still retail high because local buyers know what replacement costs. Body-on-frame SUVs remain central to this demand pattern, so Used SUVs can help illustrate the retail market discussed here.

Older sedans tell a different story. In plenty of commuter suburbs, late-model sedans face weaker demand as buyers chase crossovers. The auction price may look low, but the retail spread can widen because you're paying for inspection, financing availability, and confidence that the car won't implode on the first school run. Cheap cars are rarely cheap to retail. They need more babysitting.

EVs added another wrinkle. Some used electric vehicles have depreciated faster than comparable gas models, especially when new-EV incentives, Tesla price cuts, battery-health uncertainty, and charging access collide. A dealer may buy a used EV cheap at auction, then struggle to price it unless battery warranty status, range, software, charging equipment, and local infrastructure are crystal clear. A bargain wholesale EV can become dead inventory when the buyer pool is thin. Readers evaluating used-EV depreciation can browse Used Tesla Model Y while considering battery warranty, range, and charging factors.

Regulation piles on complexity. California emissions expectations, Northeast rust concerns, Florida flood-title vigilance, Colorado and Utah appetite for AWD, and Midwest road-salt inspection habits all move recon budgets. The same vehicle can be a buy in Georgia and a headache in Massachusetts. National averages hide that. They always do.

Scale matters too. Large groups with centralized recon centers process cars faster, negotiate parts and transport more efficiently, and price dynamically by ZIP code. Smaller independents may know their local customers better but carry higher per-unit risk. If a small dealer misbuys three cars in a row, the month gets grim in a hurry.

When the spread is fair, and when it isn't

A fair spread leaves evidence. You should see it in the inspection report, service receipts, new tires, disclosed paintwork, clean title handling, warranty coverage, honest financing terms, and a final price that matches the car's condition and the local market. A questionable spread hides behind urgency, vague fees, missing records, and theatrical shine.

Certified pre-owned cars show the legitimate version of a premium. A manufacturer-backed CPO vehicle costs more because certification has rules: age and mileage limits, inspection points, required repairs, warranty extension, brand accountability. You aren't just paying for metal. You're paying for a claim that can be enforced.

At the other end sits the lightly reconditioned auction flip: bought with visible issues, washed, listed aggressively, sold with pressure. That car may look cheaper than a CPO unit, but the risk simply moved from dealer to buyer. The price should reflect that transfer. Too often, it doesn't.

The smartest shoppers stop asking whether wholesale is "better" than retail. Better depends on execution. Retail earns its premium when recon is real, disclosures are clean, financing is competitive, and after-sale support actually exists. Wholesale-oriented buying wins when you value transparency, can tolerate a more deliberate sourcing process, and work with people who know when to walk away.

The Future of the Spread

The used-car market is settling into a calmer, more segmented phase. New-car inventory has recovered from the darkest pandemic days, trade-ins flow more normally, and wholesale values no longer behave like a meme stock every month. Affordability, though, stays strained. Higher loan rates, elevated insurance premiums, and household budget pressure keep buyers sensitive to every dollar.

That pressure should compress the spreads that can't be justified. Dealers can't lean on mystery anymore. Online listings expose stale inventory. Pricing tools update constantly. Lenders scrutinize loan-to-value ratios. Consumers compare vehicles across state lines and ask sharper questions about recon, title history, and the true out-the-door number.

Don't expect the spread to vanish, though. It shouldn't. Somebody has to inspect the car, move it, repair it, document it, finance it, warranty it, and absorb the risk when the transmission acts strange two days after delivery. The market keeps paying for certainty. It just won't keep paying indefinitely for fog.

For professionals, the mandate is brutal but clear: buy cleaner, recondition faster, disclose more, price dynamically, and turn inventory before floorplan interest eats the gross. For you, the strategy is just as practical. Compare the auction story to the retail reality. Ask what was done. Ask what wasn't. Demand the out-the-door price. If the seller can justify the gap, you'll hear specifics. If they can't, you'll hear music.

"The auction price is where the car starts. The retail sticker is where a business claims the uncertainty has been converted into value."

That's the whole game. Sometimes the claim is true. Sometimes it's just expensive lighting and a good detail.
Browse current inventory

Frequently asked questions

What does the difference between auction and retail price pay for?

It can cover auction fees, transport, reconditioning, title work, financing risk, advertising, payroll, warranty exposure, overhead, and profit. Some costs create direct buyer value, while others keep the dealership operating.

What is included in a used car's out-the-door price?

The out-the-door price includes the vehicle price plus sales tax, title, registration, state fees, doc fees, and any optional products the buyer accepts. The final amount varies by state and municipality.

Why can a dealer's spread be reasonable for one car but not another?

A spread may reflect legitimate costs such as tires, brakes, recon, transport, and title work. The same spread is harder to justify when a car was bought clean, barely serviced, and presented without meaningful improvements.

Can buyers purchase cars directly from dealer-only auctions?

Most consumers cannot bid directly at Manheim, ADESA, or closed dealer auctions because licensing, bond requirements, regulations, tax rules, arbitration procedures, and payment timelines form a barrier. A buyer-side specialist can source vehicles through dealer-only channels instead.

What should buyers ask for before purchasing a used car?

A serious buyer should request the complete out-the-door price in writing. Buyers should also review the vehicle history, seller announcements, title status, inspection information, recon needs, and financing terms.

Related Articles