Extended Warranty: Is It Worth It? An Honest Guide to Used-Car Coverage

Reading the contract before the brochure — a buyer's framework for used-car protection plans.

October 2026 · Used-Car Coverage Edition

The Short Answer

An extended warranty can be worth buying when it covers a repair that would seriously disrupt your finances, at a total price you can justify. Its value falls when exclusions remove the protection you need, deductibles absorb much of the benefit, or existing factory coverage already protects the vehicle. The useful question is whether the actual contract transfers enough financial risk to justify its cost and restrictions.

For used-car buyers across the USA, that decision belongs alongside vehicle selection, inspection and financing. Keep it separate enough to evaluate on its own: a desirable vehicle does not automatically make an accompanying protection plan a good purchase. Start with the contract, your intended ownership period and the repair expenses your household could absorb. If that price ceiling fits your budget, compare Used cars under $50k while evaluating coverage separately.

"The useful question is whether the actual contract transfers enough financial risk to justify its cost and restrictions."

The term extended warranty can describe different arrangements. Manufacturer-backed plans usually involve the automaker, while a service contract sold by a dealer may be administered by an independent company. Third-party vehicle service contracts are also marketed directly to consumers. Identify the seller, the administrator handling claims and the organization responsible for paying covered repairs. Those roles matter more than the branding on the brochure.

A manufacturer warranty generally promises to address specified defects. A purchased service contract adds protection after, or alongside, that warranty, subject to its own conditions. Compare the coverage periods directly. Ask when protection begins, which mileage limit applies and whether the quoted mileage represents an odometer ceiling or additional miles. Paying for substantial overlap can weaken the purchase, especially if you expect to sell before the additional protection becomes useful.

Read the exclusions against the vehicle you are buying

A plan may exclude maintenance, wear items, cosmetic damage, pre-existing conditions, misuse or unauthorized repairs. Batteries, sensors, seals and software can also be restricted or excluded. For a hybrid, ask about the specific battery and hybrid components; for a vehicle with driver-assistance features, ask about sensors and related electronics. Do not assume that a broad description of drivetrain or electrical coverage includes every associated part.

Reliability risk and repair-cost risk are different. A vehicle can be relatively reliable yet expensive to repair when something fails. Conversely, a component that worries you may be excluded entirely. Before paying for protection, ask a repair professional about the systems you are concerned about, then match those systems to the contract language. A vehicle category or technology alone is not enough to establish that coverage will pay off.

"Reliability risk and repair-cost risk are different."

Check what happens after a breakdown

The claims process is part of the product. Determine whether a shop needs authorization before diagnosis, disassembly or repair, and whether the administrator pays the facility directly or reimburses you. A reimbursement arrangement may still require accessible cash. Maintenance documentation, approved facilities and labor allowances can also affect a claim. Ask for a written explanation of the steps you would follow if the vehicle became undriveable away from home.

Six Questions for the Claims Desk

  • Confirm whether the deductible applies per repair, per visit or under another definition.
  • Check diagnostic and disassembly charges, including responsibility when a claim is denied.
  • Review labor-rate limits, parts allowances and any limits on total benefits.
  • Identify required maintenance records and keep them accessible.
  • Read towing and rental-car terms, including eligibility and benefit limits.
  • Ask how to challenge a denial and who provides the written decision.
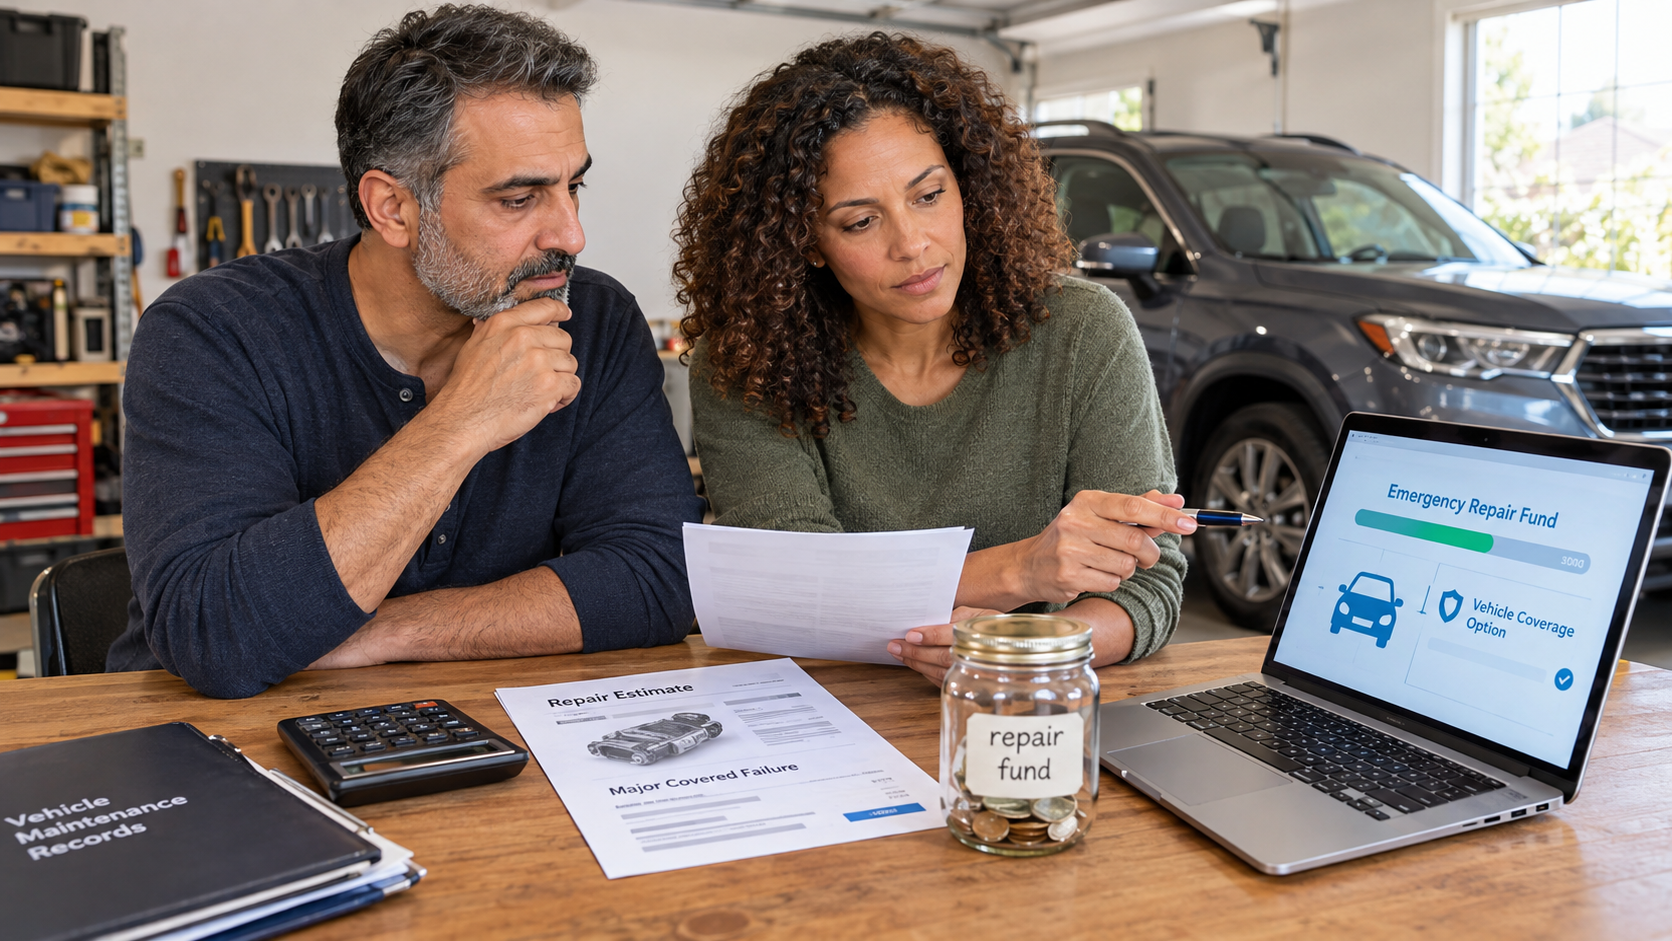
Couple comparing repair savings with extended warranty coverage before keeping a used SUV purchased through Virtual CarHub.

Coverage deserves closer consideration when a covered failure could create financial hardship, replacing the vehicle would be difficult and you intend to keep it through the useful coverage period. The strongest case combines meaningful protection with an accessible claims process and a provider whose financial standing and complaint record you can evaluate. A costly repair possibility matters only if the agreement actually covers it.

Limited emergency savings can make predictable costs appealing, but the premium should not consume money needed for deductibles, maintenance and excluded work. Ask whether you could handle those expenses after buying the plan. If the answer is no, reconsider the vehicle budget as well as the coverage. A service contract does not remove every ownership expense or guarantee that you will avoid an immediate cash outlay. If you are reconsidering your vehicle budget, explore Used cars under $40k while leaving room for maintenance and repairs.

Compare protection with money you keep

Self-insurance means retaining money for repairs rather than purchasing a contract. A dedicated repair fund preserves flexibility: it can pay for maintenance or excluded work as well as mechanical failures. Its limitation is equally practical. If an expensive repair arrives before the fund is sufficient, you must cover the shortfall. Compare the savings you have now with a repair estimate, rather than assuming future contributions are already available.

"A costly repair possibility matters only if the agreement actually covers it."

A plan becomes less attractive when you have adequate reserves, expect to sell soon, already have overlapping coverage or face a large deductible relative to likely covered repairs. Narrow authorization rules can reduce its usefulness too. Ask whether the agreement would materially change your financial exposure. Buying coverage solely because a vehicle is used skips the more important questions about condition, contract terms and your ability to pay.

Test the decision with specific repair questions

Use possible repairs as contract tests, without assuming they will happen. For a transmission concern, ask which internal components are covered and which related charges remain yours. For an electronic fault, ask how the contract treats the sensor, software and diagnostic labor separately. If you may sell early, request the cancellation calculation. These questions turn a general promise of reassurance into terms you can compare with keeping your money.

Three Ways the Decision Resolves

  • Coverage is more defensible when the relevant component is covered and the remaining expense would be manageable.
  • Self-insurance is more defensible when you can absorb repairs and the contract excludes much of what concerns you.
  • Further review is needed when authorization, eligibility or payment responsibility remains unclear.

Begin with the cash price of the contract. If it will be financed, obtain the additional interest attributable to that purchase over the proposed loan term. A monthly-payment presentation can make the underlying price less visible. Request financing comparisons with and without the service contract using otherwise consistent terms, so you can see both the payment change and the change in total borrowing cost.

A useful decision framework compares the probability of a covered failure multiplied by its covered repair cost with the premium, deductibles and uncovered expenses. Include financing interest and claim restrictions in the assessment. This is a way to organize uncertainty, not a precise prediction for your vehicle. Without credible failure probabilities, do not treat an estimate of expected savings as an established outcome.

Build a worksheet from written terms

Keep total repair cost separate from the amount the administrator would pay. A repair estimate can include diagnostic time, parts or labor beyond the contract allowance. Request an explanation of those differences for a repair you are concerned about. Otherwise, comparing the entire workshop invoice with the premium may exaggerate the plan's potential benefit.

The Six-Line Worksheet

  1. Record the contract price and any additional financing interest.
  2. Write down the start date, expiration date and mileage limit.
  3. Identify the covered components relevant to your concerns.
  4. List deductibles, diagnostic obligations, labor limits and excluded charges.
  5. Compare potential contract payments with the savings available for repairs.
  6. Review how an early sale or cancellation would change the cost.

Expected value and household affordability answer different questions. You might reasonably accept a cost to reduce exposure to a financially disruptive repair, even when you cannot establish that the plan will save money on average. But the protection must address that disruption: a contract requiring substantial reimbursement spending or excluding the feared component may offer little help when you need it.

"Expected value and household affordability answer different questions."

Cancellation deserves the same attention as coverage. Ask whether cancellation is permitted, how any prorated refund is calculated, whether deductions apply and where the money goes if the contract was financed. Do not assume a refund reaches you directly or changes your monthly payment. Also consider the value of retaining accessible savings throughout ownership. Terms vary—confirm them in writing before relying on a future refund.

Buyer-Side Practice

Virtual CarHub: Evaluating Coverage During a Wholesale Vehicle Purchase

VirtualCarHub.com sources used cars, trucks and SUVs for consumers through dealer-only auction channels, inspects them, and handles financing, paperwork and delivery. Its model has no retail lot, no markup and no commissioned sales. When evaluating a purchase through Virtual CarHub in the USA, apply the same independent scrutiny to any service contract you consider: request its price, eligibility rules and complete terms separately from the vehicle decision. To explore SUV options, browse Used SUVs and assess any service contract separately.

For professionals coordinating buyer-side wholesale acquisition, a useful practice is to assemble the vehicle and coverage documents before asking the buyer to decide. Review the inspection findings, available maintenance history, remaining manufacturer protection and proposed contract together. Because pre-existing conditions may be excluded, ask the administrator to address relevant inspection findings in writing. Keep promises about the vehicle's condition distinct from promises made by a separate contract provider.

Make location a practical contract question

Across the USA, evaluate where repairs could actually take place. A rural buyer should check the distance to an approved facility and the towing allowance. A metropolitan buyer should compare a local shop's estimate with the contract's labor allowance. For a vehicle used in northern winters, Southwestern heat or coastal conditions, ask specifically how corrosion, cooling-system problems, batteries and storm-related damage are treated. Confirm the terms instead of assuming local conditions make a claim eligible.

Verify the seller and applicable rules

Service contracts and insurance products can fall under different regulatory frameworks, so confirm the rules applicable in your state rather than assuming a nationwide cancellation or refund entitlement. Ask the relevant state regulator or attorney general's office where to verify requirements and raise concerns. Official-looking mailers, unidentified calls about expiring coverage, claims that protection is mandatory and refusal to provide the contract are reasons to stop and independently verify the offer. If a seller says financing requires coverage, request the lender's requirement in writing and verify it directly.

Before signing, you should be able to explain what you are buying, what remains your responsibility and how a claim would work. An extended warranty is worth considering when it meaningfully limits a repair expense you could not comfortably absorb. If its cost, exclusions or procedures leave that exposure largely intact, keeping money available for repairs may be the more useful choice.

Before You Sign: The Final Checklist

  • Obtain the complete contract before payment and verify the seller independently.
  • Confirm the administrator, payment responsibility and vehicle eligibility.
  • Compare the agreement with remaining manufacturer coverage.
  • Document the total price, financing cost, deductible and coverage limits.
  • Check approved repair access near home and where you travel.
  • Clarify cancellation rights, refund calculations and refund destination.
  • Keep the signed agreement, inspection documentation and maintenance records together.
Browse current inventory

Frequently asked questions

When is an extended warranty worth considering for a used car?

Coverage deserves closer consideration when a covered failure could cause financial hardship, replacing the vehicle would be difficult and you plan to keep it through the useful coverage period. The contract should provide meaningful protection and an accessible claims process.

What might a used-car service contract exclude?

A plan may exclude maintenance, wear items, cosmetic damage, pre-existing conditions, misuse or unauthorized repairs. Batteries, sensors, seals and software may also be restricted or excluded, so check the specific components in the contract.

Should I save for repairs instead of buying coverage?

A dedicated repair fund can pay for maintenance, excluded work and mechanical failures. However, if an expensive repair arrives before the fund is sufficient, you must cover the shortfall. Compare your current savings with a repair estimate.

How does financing a service contract affect its cost?

Financing adds interest attributable to the contract purchase over the loan term. Request comparisons with and without the contract using otherwise consistent terms to see both the payment difference and the change in total borrowing cost.

Can I cancel a service contract and get a refund?

Terms vary, so ask whether cancellation is permitted, how any prorated refund is calculated and whether deductions apply. If the contract was financed, confirm where the refund goes; do not assume it reaches you directly or changes your monthly payment.

Related Articles