Best Time of Year to Buy a Used Car

Seasonal Pricing Patterns and Smart Timing Strategies for the Prepared Buyer

USED-CAR BUYING EDITION — AUGUST 2026

In the used-car market, timing doesn't work like a magic coupon. It works more like weather. Pressure builds, demand shifts, inventory moves through channels most shoppers never see, and then, quietly, prices soften in one market while hardening in another.

For buyers in the USA, the broad answer holds fairly steady: late fall and winter, especially November through February, tend to offer the strongest buying opportunities. Not every vehicle will be cheaper. Not every seller will blink. But buyer traffic slows, dealers want aging inventory off their books, and wholesale auction values often tell a more honest story than the retail sticker on the windshield.

Spring flips the script. Tax refunds arrive. College graduates need transportation. Families start imagining road trips, summer camps, beach houses. Demand wakes up. By May and June, the same three-row SUV that felt negotiable in December can suddenly have three interested buyers and a manager who won't return your call. That's not coincidence. That's seasonality. Families shopping for practical transportation may want to compare Used SUVs while demand is rising in spring.

"The best time to buy is when supply is high and buyer urgency is low."

The trick is learning how car pricing really works before you fall in love with a color, a trim package, or a monthly payment. Retail listings are the visible surface. Underneath, wholesale values, reconditioning costs, financing, dealer fees, regional supply, and days-on-market drive the deal. Ignore those forces and you might save $700 on the sticker while overpaying $2,000 through rate, add-ons, or a vehicle that's about to need tires.

Transparent car pricing in USA markets starts with a less romantic idea. The best time to buy is when supply is high and buyer urgency is low. That window usually opens when most people are busy spending money on everything except cars. If you want the deeper mechanics behind that pattern, this breakdown of seasonal pricing patterns that actually matter is a useful companion read.
Why Winter Usually Favors Buyers

The Quiet Months on the Lot

January and February can feel strange on a dealership lot. The holiday decorations are gone, credit card bills are landing, and casual shoppers have mostly vanished. Sales teams still have targets. Floorplan costs still tick along. Vehicles that looked fresh in October may now be 75 or 90 days old, which is an eternity for a used unit parked on a retail lot.

That aging inventory matters more than most buyers realize. Dealers don't want used cars to sit indefinitely, because each extra week brings carrying cost, depreciation risk, and the chance that wholesale values will move against them. A vehicle bought at auction in September, based on a hot late-summer market, can look overpriced by January if comparable units have slipped. The dealer can hold firm and hope. Or take a slimmer gross and move the metal.

December deserves attention too, though not for the cartoonish reason people assume. Sure, year-end sales goals create pressure. The better opportunity usually comes from something quieter: lower showroom traffic, trade-ins from year-end new-car deals, and managers cleaning up aged inventory before financial reporting closes. The final week of December can pay off for a disciplined buyer. It can also be chaos, so walking in unprepared is a mistake.

"Month matters. Data matters more."

Late fall carries its own rhythm. September and October sit between seasons. Summer demand cools, newer model-year vehicles pull attention, and dealers reassess what's worth keeping through winter. In plenty of USA markets, that's when sedans, older crossovers, and high-mileage commuters become negotiable. Trucks and all-wheel-drive SUVs are trickier, especially in snow states where buyers suddenly remember that February exists. Late fall may create negotiating room on Used Sedans, especially as summer demand cools.

Here's the sharper question the smartest buyers ask. Not "Is this a good month?" but "Is this vehicle cheap relative to today's wholesale car valuation, local supply, its condition, and the seller's motivation?" Month matters. Data matters more.

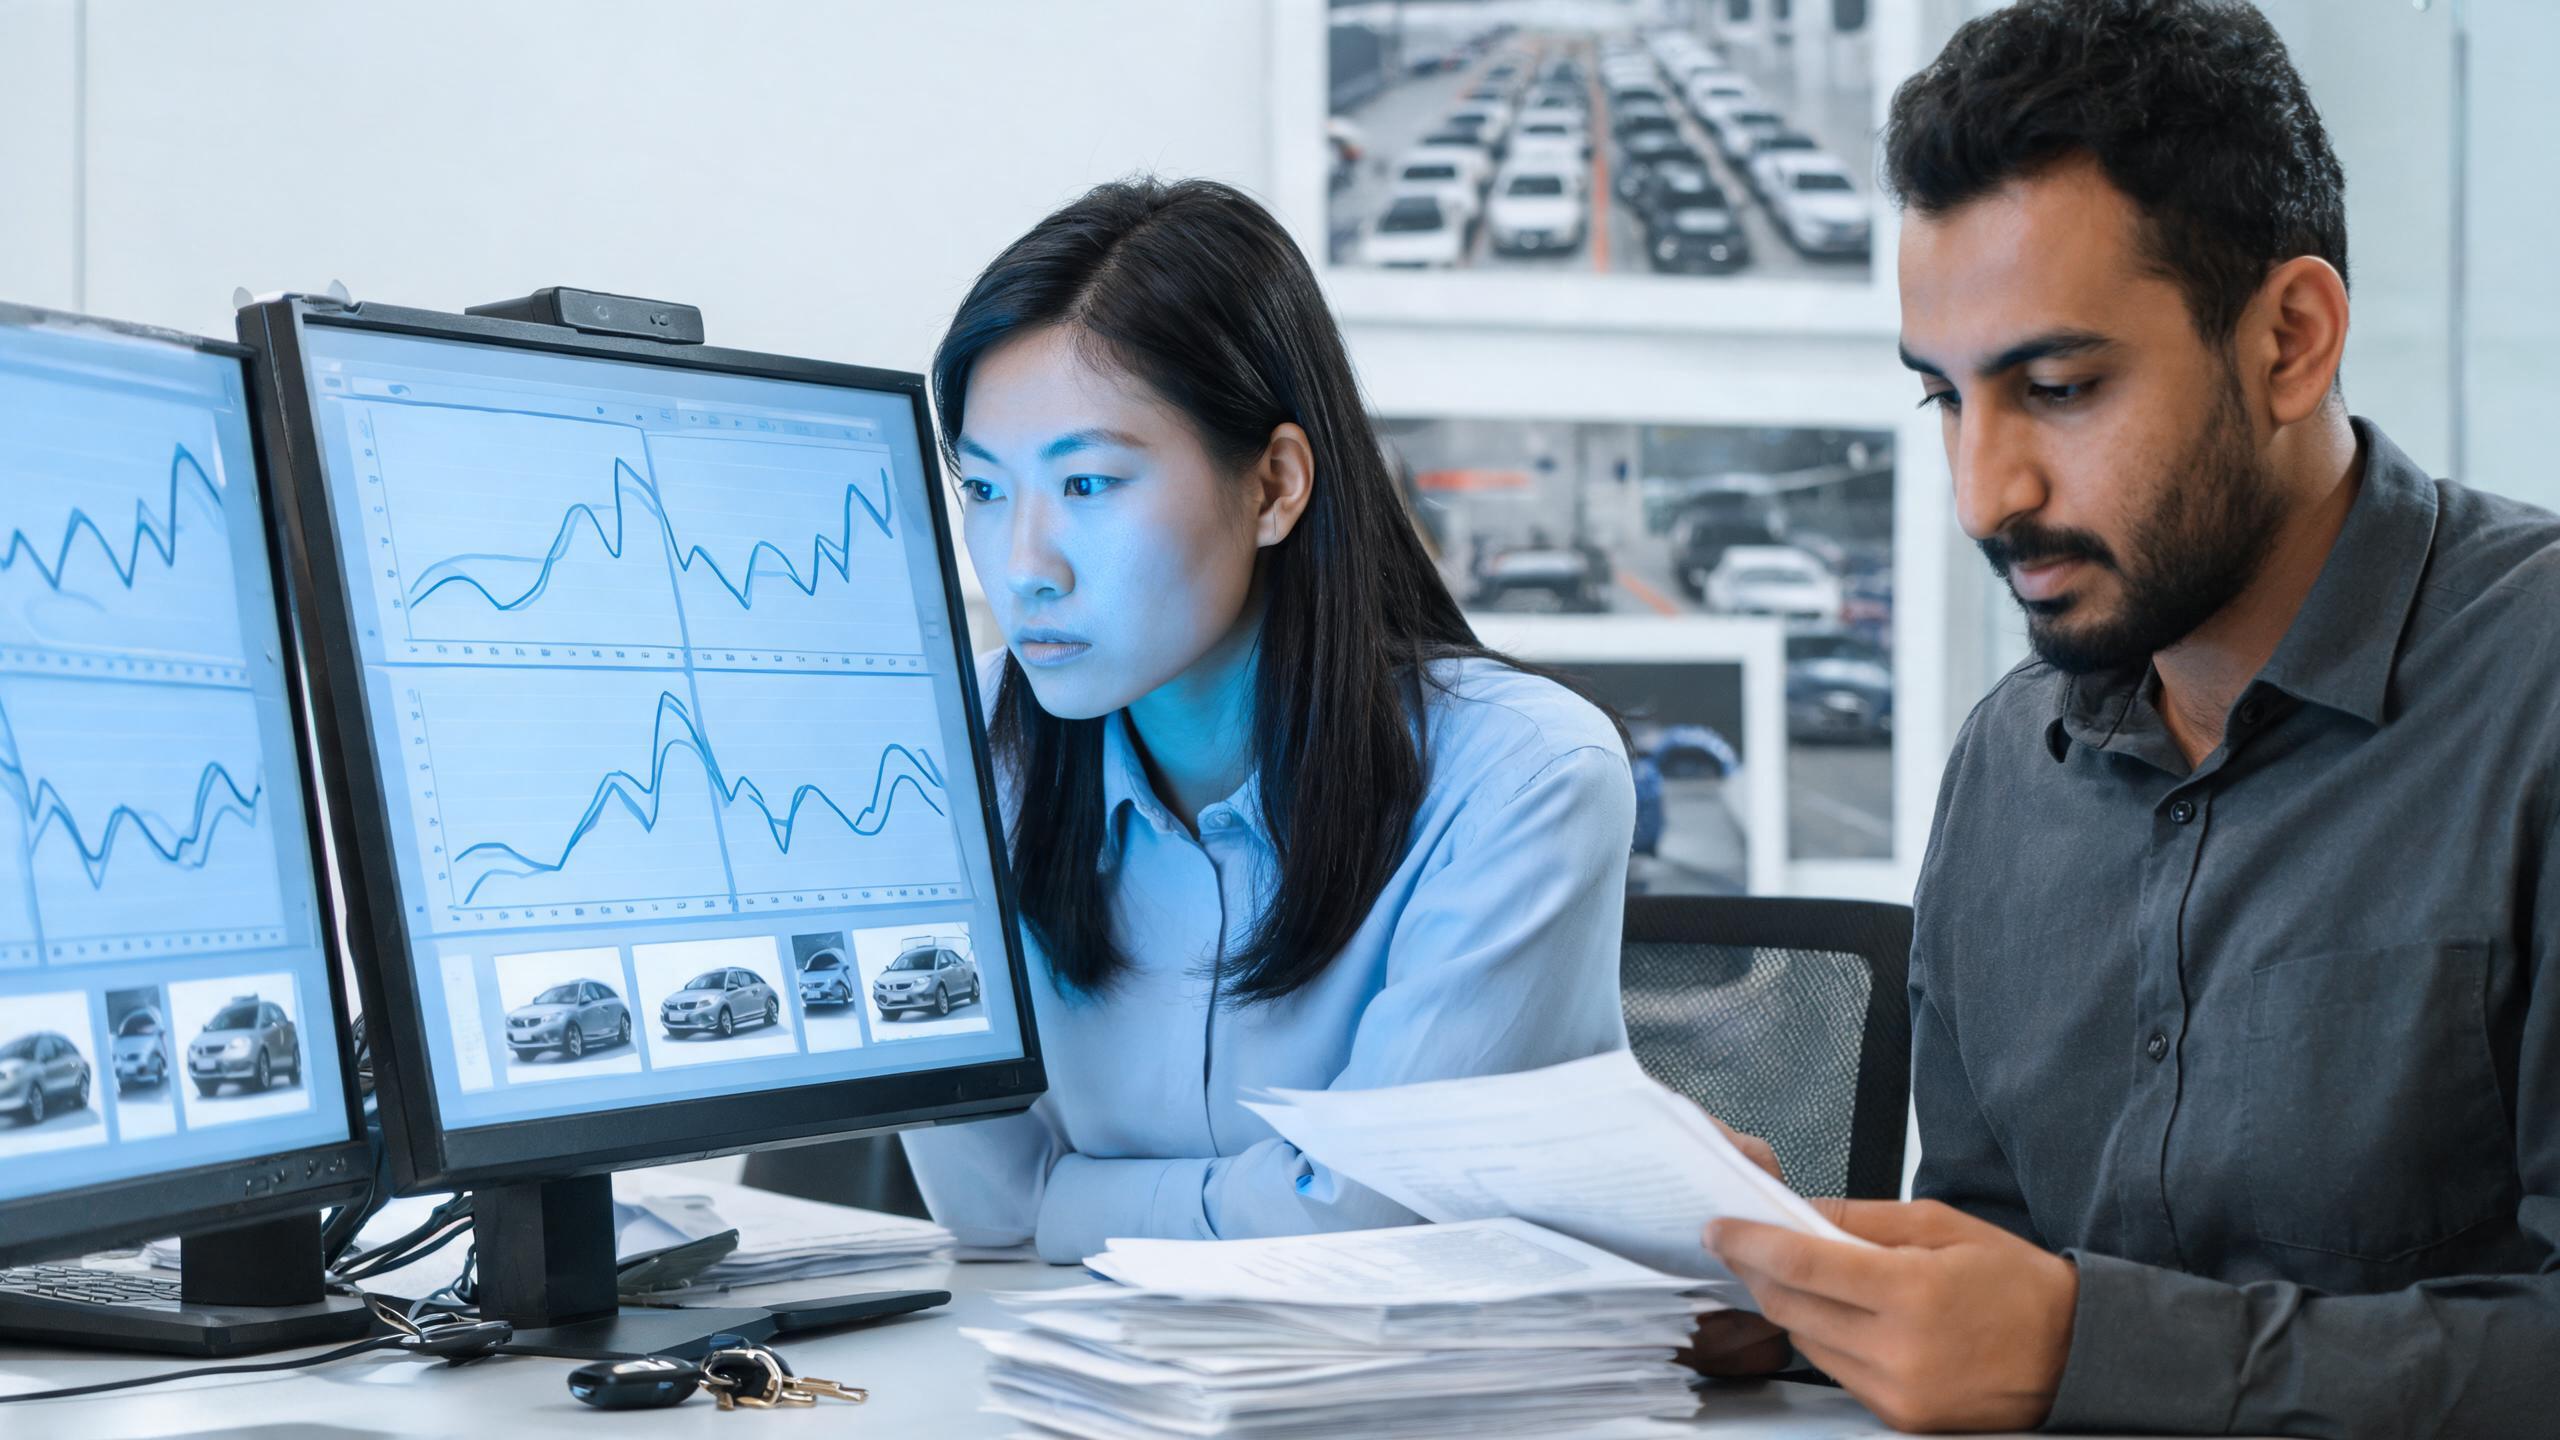
Dealership analysts comparing wholesale car valuation data to retail listings to show how car pricing really works.

How Car Pricing Really Works

Most people judge a used car by the asking price they see online. Understandable. Also incomplete. Retail prices are managed, massaged, and sometimes stubbornly stale. Wholesale auction prices react quickly to supply and demand. When late-model SUVs flood the auction lanes after a wave of lease returns, the wholesale market feels it first. Retail lots can take weeks to catch up.

That lag is where opportunity lives. A buyer who understands fair market value used car pricing can spot when a dealer is still advertising last month's optimism. The logic runs both ways. If wholesale values jump because a model is scarce, a retail listing that looked average two weeks ago might suddenly be a legitimate deal. The market doesn't wait for your spreadsheet to feel tidy.

Dealer-only auctions are the bloodstream of the used-car industry. Franchised dealers offload trade-ins they don't want to retail. Rental fleets cycle out inventory. Banks dispose of repossessions. Lease companies release off-lease vehicles, and independent dealers fight over units they can recondition. That's where wholesale car valuation stops being theoretical and gets brutally practical: what did similar vehicles actually bring under the hammer this week?

The Buyer-Side Premise

VirtualCarHub.com works from a different angle. Instead of steering you toward inventory already sitting on a lot, it sources cars, trucks, and SUVs through dealer-only auction channels, arranges inspection, and handles financing, paperwork, and delivery without the retail-lot markup or the commissioned sales routine. That doesn't erase market forces. Nothing does. It just gives you visibility into the acquisition side, where the pricing signals show up first.

Here's the thing about upfront car pricing. It isn't one number printed in bold. It's a chain of inputs: acquisition cost, auction fees, transportation, reconditioning, tires, brakes, title processing, state taxes, documentation fees, financing terms, warranty decisions. A price that looks low can hide a rough vehicle. A price that looks slightly higher can include a cleaner history, better tires, and lower risk. Cheap gets expensive fast.

Financing has become a bigger part of the affordability story across the USA, because Federal Reserve rate policy feeds directly into auto-loan rates and monthly payments. Negotiate $1,200 off the price, then accept a high APR without shopping credit unions, banks, or preapproval, and you'll hand that savings right back over the life of the loan. The best seasonal strategy falls apart when the financing is lazy.

Where You Live Changes the Deal

Regional Timing and Buyer Psychology

Used-car pricing is local in ways national averages flatten. A four-wheel-drive pickup in Minnesota before the first serious snowstorm isn't the same product as that pickup in Phoenix in May. Same VIN category. Completely different buyer psychology. The market knows.

Up north, all-wheel-drive crossovers, Subarus, body-on-frame SUVs, and pickups see firmer demand as autumn turns cold. Shoppers who ignored their bald tires and rear-wheel-drive sedan all summer suddenly crave traction. Dealers know it. Waiting until deep winter can help in those markets, but the sweet spot may be after the first wave of panic buying passes, not before it starts. Northern buyers may see firmer demand for Used Subaru as autumn turns cold.

Sun Belt markets tend to carry broader supplies of pickups and SUVs, partly because those vehicles dominate local taste and fleet use. Texas, Florida, Arizona, Georgia, and the Carolinas produce different inventory patterns than dense Northeastern metros. Coastal cities may show higher transaction prices but more selection, especially for luxury imports, hybrids, and off-lease vehicles. Rural markets can have fewer choices and surprisingly sticky prices, because replacement inventory is harder to source.

"A winter bargain isn't a bargain if the undercarriage spent five seasons marinating in road brine."

Then there's weather history. Flood exposure along parts of the Gulf Coast, rust in the Upper Midwest and Northeast, hail damage in Colorado and the Plains, salt-air corrosion near the coasts. All of it moves value. A cheap car with a rotted undercarriage isn't cheap. Inspection standards have to follow geography.

Buyers willing to compare nearby markets often find leverage. A Chicago family shopping for a front-wheel-drive sedan may score better options in Indiana or Wisconsin. Someone hunting a hybrid in a smaller inland market might find more choices around a coastal metro with heavier lease turnover. Widen the search intelligently, though. Transportation cost, state inspection rules, emissions compliance, title timing, and sales-tax treatment can eat the apparent discount. If you're weighing whether to sell your current ride first, this look at trade-in vs. private sale and car depreciation lays out the tradeoffs.

Strategies That Actually Save Money

Timing Levers Worth Pulling

End-of-month shopping is real, but only when the vehicle and seller are already set up for a deal. No dealer loses money on a scarce, fast-turning Toyota Tacoma just because the calendar says the 30th. But a 64-day-old crossover with two similar units arriving next week? That's a different conversation. A scarce Used Toyota Tacoma may not become cheaper simply because the month is ending.

End-of-quarter timing sharpens the pressure. March, June, September, and December carry weight for stores watching volume targets, manufacturer programs, lender relationships, and internal metrics. December adds year-end accounting on top. Even so, don't wander into a showroom at 6 p.m. on New Year's Eve expecting strategy to bloom out of good vibes. Know the market first.

Days-on-market may be the single most underrated signal in used-car buying. A vehicle listed for seven days has little give unless it's mispriced or flawed. One sitting 45 days is worth a careful offer. Past 60, especially in a softening wholesale segment, the seller may want a clean transaction more than the perfect buyer. That's where polite, evidence-based negotiation beats theatrical haggling every time.

Preapproval isn't optional. Banks, credit unions, and online lenders give you a baseline before you ever discuss dealership financing. Maybe the dealer beats your rate. Great, let them. Just don't let a seasonal discount melt into a monthly-payment shell game where loan term, rate, and add-ons blur the true cost.

A Practical Buying Plan, Month by Month

  1. Two to three months out: Pick three acceptable models, not one dream configuration. Research common failures and ownership costs.
  2. Six weeks out: Track comparable listings within 100 to 300 miles, depending on your region and vehicle type.
  3. Thirty days out: Get financing preapproval; estimate taxes, registration, insurance, and delivery.
  4. Two weeks out: Watch days-on-market and wholesale indicators. If prices are falling, don't rush unless the unit is exceptional.
  5. Final week: Make offers on total out-the-door cost, never monthly payment.

Inspection ranks right up there with timing. Dealer-only auction channels use condition reports, but a report is no substitute for mechanical due diligence. Check tire date codes, brake wear, accident-quality repairs, oil leaks, suspension noise, infotainment failures, open recalls, and mismatched paint. On hybrids and EVs, battery health and charging equipment matter. On diesels, emissions-system repairs can be punishingly expensive.

This is where VirtualCarHub.com's buyer-side acquisition approach earns its keep. The question shifts from "When is the lot discount biggest?" to "When is the wholesale lane producing the right unit at the right valuation?" If you dislike commissioned sales pressure, that distinction is more than philosophy. It changes how you shop.

What to Avoid, Even in the Best Season

Seasonal timing breeds overconfidence, and overconfidence is dangerous. A bad vehicle bought in December is still a bad vehicle. It just comes with a better story. The market is full of cars that look attractively priced because they carry accident history, deferred maintenance, odometer inconsistencies, branded-title risk, or reconditioning shortcuts that never show up in glossy photos.

Watch the fees. Documentation fees and dealer charges vary widely by state, and some states police them harder than others. Advertising fees, nitrogen, paint protection, security etching, GPS recovery devices, and other add-ons can turn upfront car pricing into pure theater when they surface late in the process. Demand an out-the-door figure in writing.

Be wary of long loan terms. A 72- or 84-month loan can make an expensive used SUV feel manageable, but depreciation doesn't care about your comfort. If the vehicle needs major repairs while you're still underwater, the bargain becomes a trap. That risk climbs when rates are elevated and lenders price older, higher-mileage units aggressively.

"Timing opens the door. Knowledge gets you through it."

Don't treat national fair market value used car tools as gospel either. They're solid starting points, nothing more. Trim differences, certification status, accident history, drivetrain, color, mileage distribution, and regional demand all shift value. A white work truck in Dallas, a hybrid hatchback in Los Angeles, and an AWD wagon in Vermont live in entirely different pricing ecosystems.

The best buyers pair patience with readiness. They know the seasonal pattern, lock in financing early, inspect without mercy, weigh wholesale against retail, and move fast when the right unit shows up. No drama. No showroom mythology. Just disciplined acquisition. For a fuller walkthrough of the timing playbook, keep this guide to seasonal pricing patterns and timing strategies handy.

So when is the best time of year to buy a used car? Usually late fall through winter, with November, December, January, and February offering the most consistent leverage. But the real deal belongs to whoever understands the market beneath the calendar. Timing opens the door. Knowledge gets you through it.

Browse current inventory

Frequently asked questions

What time of year is usually best for buying a used car?

Late fall and winter, especially November through February, tend to offer the strongest buying opportunities. Lower buyer traffic and aging inventory can create more negotiating room.

Why can December be a good month to buy a used car?

Lower showroom traffic, trade-ins from year-end new-car deals, and managers cleaning up aged inventory can create opportunities. The final week can also be chaotic, so preparation matters.

How does days-on-market affect negotiation?

A vehicle listed for seven days usually has little flexibility unless it is mispriced or flawed. Vehicles sitting 45 days or more may justify a careful offer, especially past 60 days in a softening wholesale segment.

What should I check besides the asking price?

Consider wholesale values, reconditioning costs, financing, dealer fees, regional supply, condition, and days-on-market. Also review the vehicle's history, tires, brakes, recalls, and possible mechanical problems.

Related Articles